China’s departure VAT-refund scheme includes “refund upon purchase” at participating stores. Receiving an advance in a shop does not remove the departure conditions. The 2025 expansion has since been supplemented by 2026 rules for paperless processing, checks and cross-region handling.[1]
Key Highlights of the New VAT Refund Policy
1. Instant Refunds at Point of Purchase
At an instant-refund shop, eligible visitors sign an agreement and use their own credit card for pre-authorisation. Read its departure and guarantee conditions before accepting the advance.[2]
2. Lowered Minimum Purchase Threshold
The threshold is RMB 200 for the same eligible visitor at the same participating store on the same day. Other eligibility conditions still apply.[3]
3. Increased Refund Cap
Cash refunds are available up to RMB 20,000 under the published policy; larger refunds use bank transfer. This is a refund-payment limit, not a shopping allowance.[4]
4. Expanded Network of Tax-Free Stores
China plans to increase the number of tax refund stores in key areas such as shopping districts, tourist attractions, airports, and hotels, making the refund process more convenient for travelers.
5. Simplified Procedures and Digital Integration
From July 2026, electronic forms and invoices can support paperless processing. The national service code also supports information retrieval and progress checks. Paper documents remain available on request. Follow the system’s verification instructions; no five-minute completion time is guaranteed.[5]
Eligibility Criteria for Tourists
To qualify for the instant VAT refund:
- Eligible visitors include foreign nationals and residents of Hong Kong, Macao and Taiwan who meet the mainland-stay conditions; use an accepted identity/travel document.[6]
- Stay and purchase timing: Mainland residence must not exceed 183 consecutive days before departure; ordinary refund goods must leave within 90 days of purchase. The instant-refund agreement has a separate, shorter departure deadline.[7]
- Designated Retailers: Use a registered departure-refund shop and confirm whether it also offers the instant-refund service for your purchase.[16]
- Goods must be unused and personally carried or checked out with the traveller. From July 1, 2026, applications below RMB 10,000 in sales are subject to sampling for physical checks; RMB 10,000 or more remains checked individually. Keep goods accessible and follow the departure system’s instruction.[8]
- For instant refunds, the national departure deadline is 28 days, replacing old local examples such as 17 days. Confirm the eligible exit port and agency arrangements with the shop; approved ports can include air, sea and land ports, not only airports.[9]
Impact on Tourism and Economy
This policy shift is part of China’s broader strategy to stimulate domestic consumption and enhance its appeal as a tourist destination. By simplifying the tax refund process and providing immediate financial incentives, China aims to encourage increased spending by foreign visitors, thereby supporting economic growth amid global trade tensions.
FAQs
1.What is the new VAT refund policy for foreign tourists in China?
Eligible visitors can receive an advance at participating instant-refund stores, then complete the required departure process. Ordinary departure refunds also remain available.[10]
2.What is the minimum purchase amount to qualify for a VAT refund?
RMB 200 at the same participating store on the same day for the same eligible visitor, subject to the other conditions.[11]
3.How much can I get back through the VAT refund?
The net refund depends on the goods’ applicable refund rate and the agency fee. Ask the refund shop to show the calculation for your exact item; the old “13% VAT × 80%” example was not the scheme’s calculation.[12]
4.What do I need to do to receive the refund?
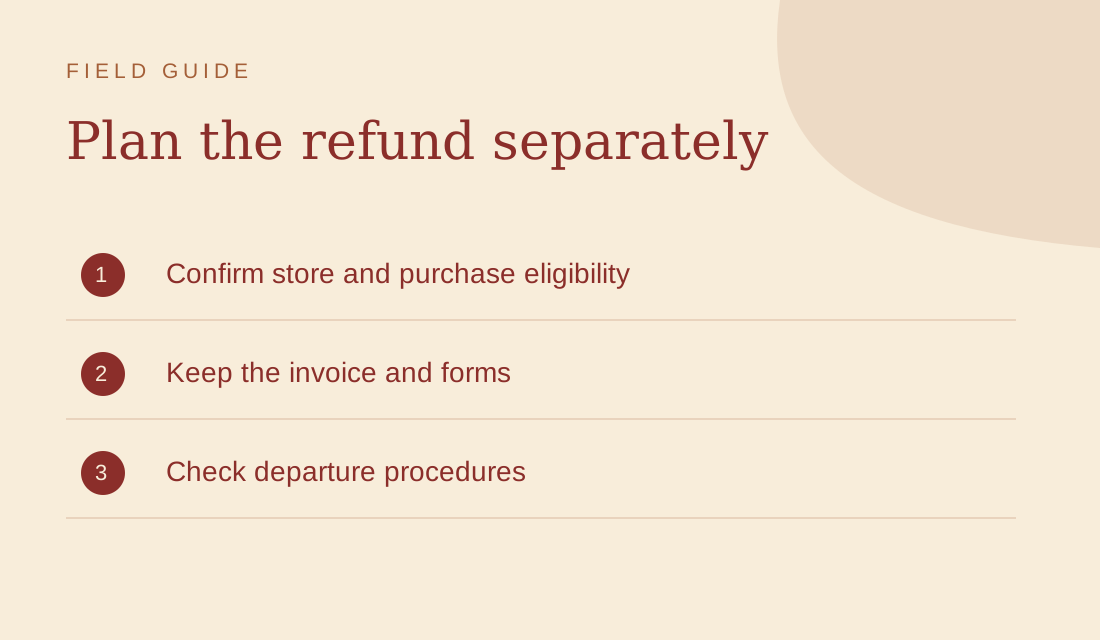
Ask the shop to confirm eligibility, issue the refund records and explain any instant-refund agreement. Keep the unused goods and records available, follow the exit-port verification instructions, and complete the refund agency’s departure procedure.[13]
5.Are all stores in China offering this instant VAT refund?
No. A registered departure-refund shop does not necessarily provide the instant-refund service. Confirm both the shop and the specific purchase before paying.[14]
More
1.For more detailed information and updates on China’s tax refund policies, you can visit the official website of the State Taxation Administration: China Taxation Administration.
China entry and transit requirements — see the updated guide
Notes & sources
These notes support the specific corrections above. They do not mean that every sentence, future opening time or individual eligibility has been verified.
Correction notes and source scope
Remove false claim that the departure process was eliminated.
MOFCOM: 2026 departure-refund noticeSource checked 2026-10-31Explain conditional advance rather than unconditional point-of-sale refund.
State Taxation Administration: departure refund FAQSource checked 2026-10-31Correct threshold context; remove stale exchange conversion.
State Taxation Administration: 2025 refund reformSource checked 2026-10-31Clarify cap type and remove stale USD conversion.
Shanghai Taxation Administration: departure-refund guideSource checked 2026-10-31Replace false passport-only/instant guarantee with actual 2026 process.
STA July 2026 notice via MOFCOM refund platformSource checked 2026-10-31Correct overly vague nonresident/visa definition.
State Taxation Administration: departure refund FAQSource checked 2026-10-31Distinguish stay, ordinary purchase and instant-refund clocks.
Shanghai Taxation Administration: departure-refund guideSource checked 2026-10-31Update blanket physical-presentation wording precisely.
Shanghai Taxation Administration: departure-refund guide MOFCOM: 2026 departure-refund noticeSource checked 2026-10-31Update obsolete deadline and airport-only restriction.
MOFCOM: 2026 departure-refund notice State Taxation Administration: departure refund FAQSource checked 2026-10-31Correct claim instant refund replaced departure scheme.
State Taxation Administration: departure refund FAQSource checked 2026-10-31Remove stale dollar conversion; retain verified threshold.
State Taxation Administration: 2025 refund reformSource checked 2026-10-31Remove incorrect invented refund formula; exact product rate not universal.
Shanghai Taxation Administration: departure-refund guideSource checked 2026-10-31Replace incomplete procedure.
STA July 2026 notice via MOFCOM refund platformSource checked 2026-10-31Distinguish refund shop registration from instant-refund service.
State Taxation Administration: departure refund FAQSource checked 2026-10-31Replace obsolete 144-hour/current-year link label; keep existing internal destination for the separately revised entry page.
Editorial correction; no new factual-verification date claimed.Distinguish shop registration from the additional instant service.
State Taxation Administration: departure refund FAQSource checked 2026-10-31
- MOFCOM: 2026 departure-refund notice
28-day instant-refund deadline; small-claim sampling and paperless process.
Checked 2026-10-31 - State Taxation Administration: departure refund FAQ
Eligible travellers, port types and conditional instant-refund advance.
Checked 2026-10-31 - State Taxation Administration: 2025 refund reform
RMB 200 threshold and cash-refund cap.
Checked 2026-10-31 - Shanghai Taxation Administration: departure-refund guide
Unused goods, purchase/stay timing, calculation and payment methods; later 2026 processing rules take precedence.
Checked 2026-10-31 - STA July 2026 notice via MOFCOM refund platform
Electronic records, paper option, service code and cross-region processing.
Checked 2026-10-31